The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...


The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
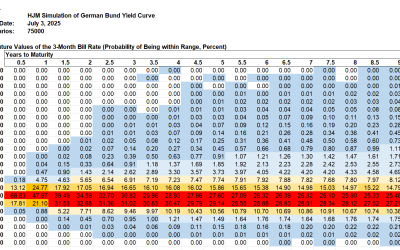
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
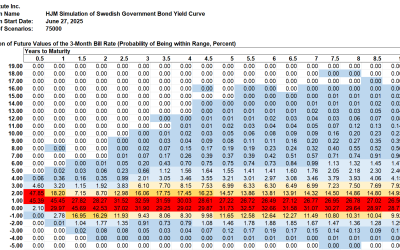
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
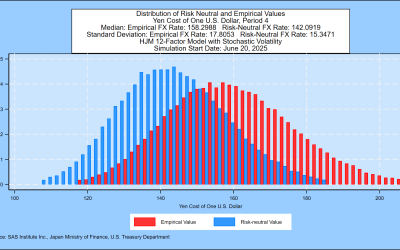
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
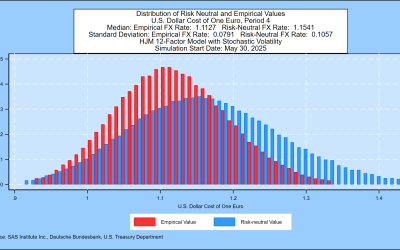
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
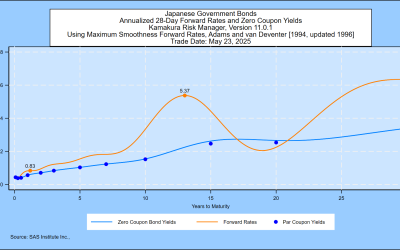
Summary The median level for the yen-U.S. dollar exchange rate is 148.09 one year from now, compared to 151.10 last week,...

Summary The median level for the yen-U.S. dollar exchange rate is 151.10 one year from now, compared to 150.16 last week,...

Summary The median level for the yen-U.S. dollar exchange rate is 150.16 one year from now, compared to 147.31 last week,...

Summary The median level for the yen-U.S. dollar exchange rate is 145.90 one year from now, compared to 143.61 last week,...

Summary The median level for the yen-U.S. dollar exchange rate is 143.61 one year from now, compared to 145.18 last week,...

Summary The median level for the yen-U.S. dollar exchange rate is 145.18 one year from now, compared to 148.58 last week,...

Summary The median level for the yen-U.S. dollar exchange rate is 148.58 one year from now, compared to 149.89 last week,...