The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
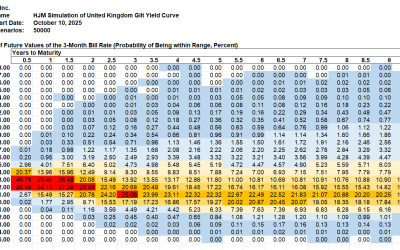


The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
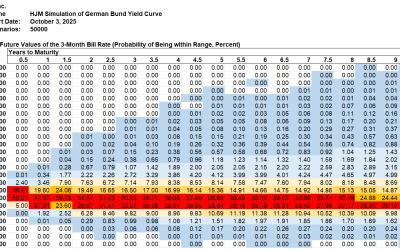
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
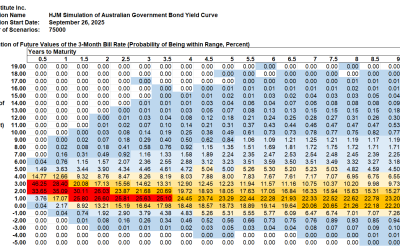
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
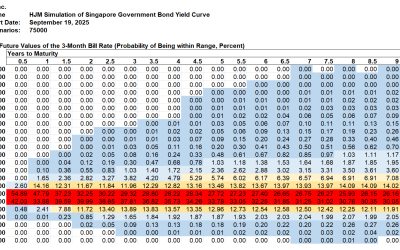
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
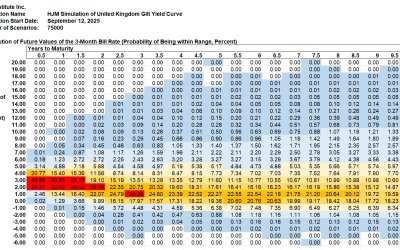
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
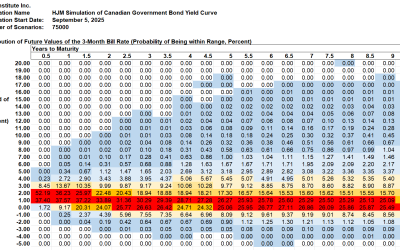
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
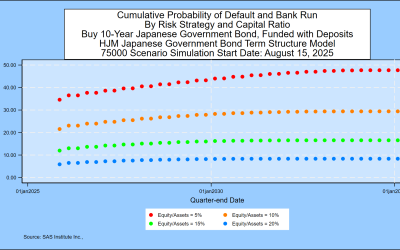
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
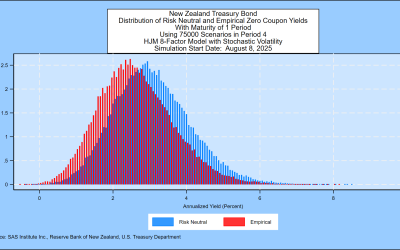
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...

The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...

The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
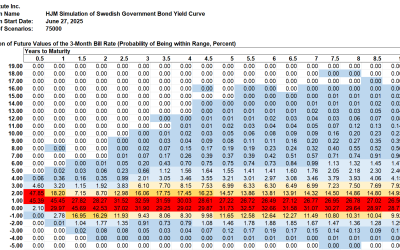
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...

Summary One-month forward Gilt rates peaked at 6.64% this week, compared to 6.76% the previous week. The 2-year/10-year United...