The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...


The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is down4% to 36% today. The probability...
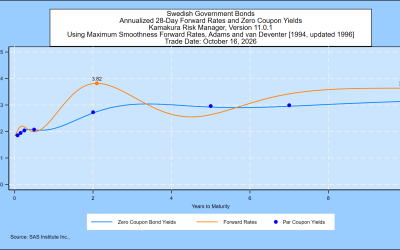
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
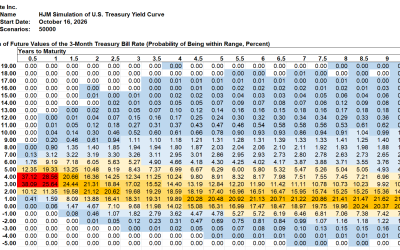
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is at 40% today. The probability that...
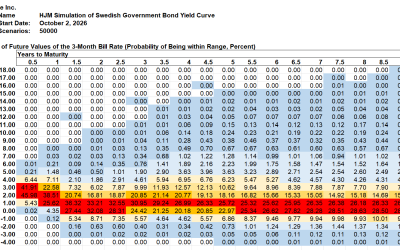
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
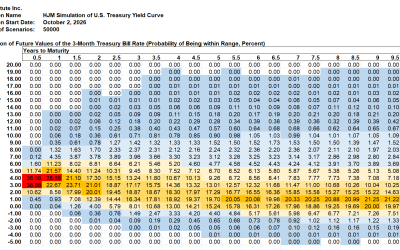
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is up 5% to 48% today. The probability...
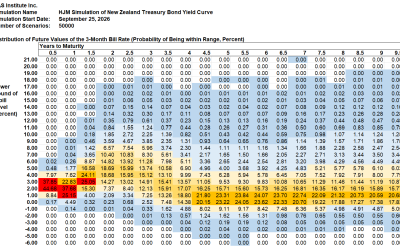
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
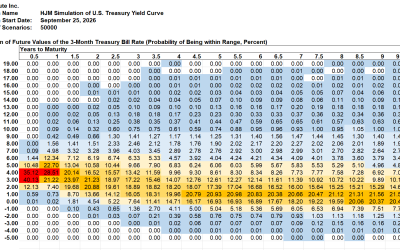
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is up 7% to 43% today. The probability...
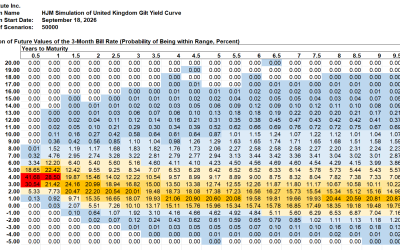
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
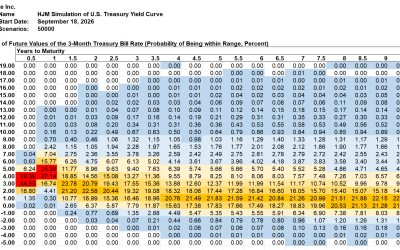
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is up 1% to 36% today. The probability...
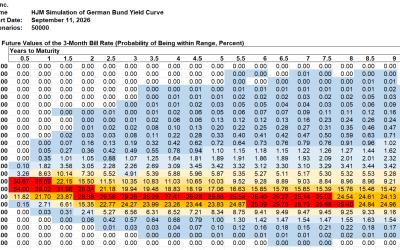
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
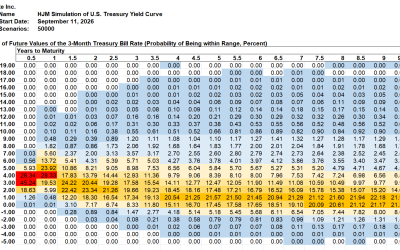
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is up 7% to 35% today. The probability...