The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
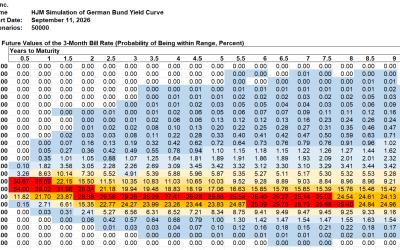


The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
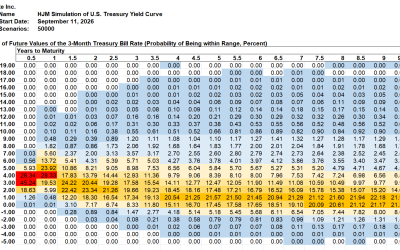
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is up 7% to 35% today. The probability...
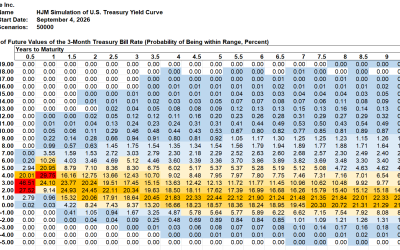
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is 28% today. The probability that the...
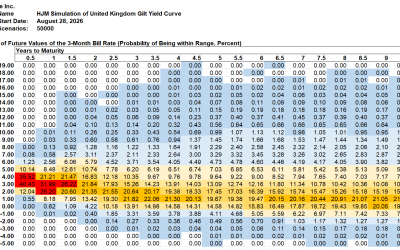
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
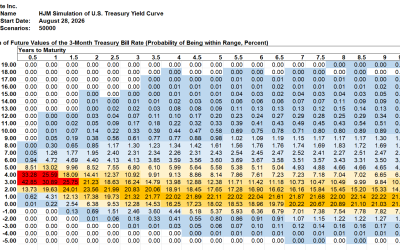
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is 28% today. The most likely range for...
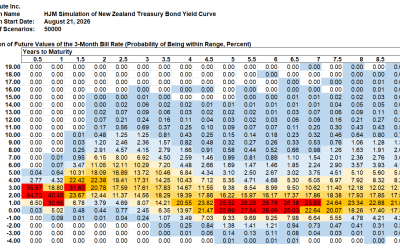
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
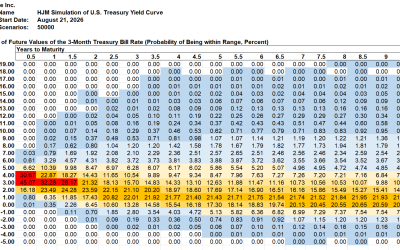
Summary The most likely range for 3-month bill yields in 10 years remained at the 1% to 2% range this week. The probability of...

The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...

Summary The most likely range for 3-month bill yields in 10 years remained at the 1% to 2% range this week. The probability of...

Summary The most likely range for 3-month bill yields in 10 years remained at the 1% to 2% range this week. The probability of...

Summary The most likely range for 3-month bill yields in 10 years remained at the 1% to 2% range this week. The probability of...
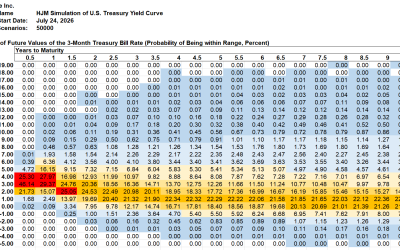
Summary The most likely range for 3-month bill yields in 10 years remained at the 1% to 2% range this week. The probability of...