

Research
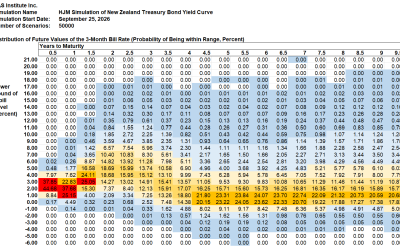
HJM++© Correlated Government Yield and Foreign Exchange Rate Simulations for Asia-Pacific, Europe and North America, September 25, 2026
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
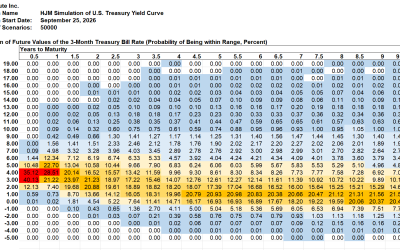
SAS Weekly Treasury Simulation, September 25, 2026: Probability of 3-Month Bill Yield Over 4% in One Year Down 8% to 71%
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is up 7% to 43% today. The probability...
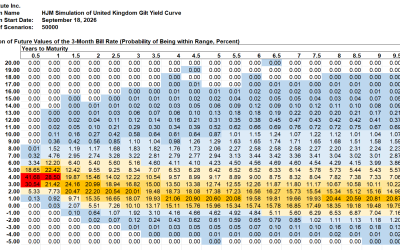
HJM++© Correlated Government Yield and Foreign Exchange Rate Simulations for Asia-Pacific, Europe and North America, September 18, 2026
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
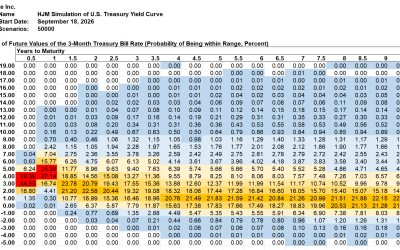
SAS Weekly Treasury Simulation, September 18, 2026: Probability of 3-Month Bill Yield Over 4% in One Year Up 5% to 79%
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is up 1% to 36% today. The probability...
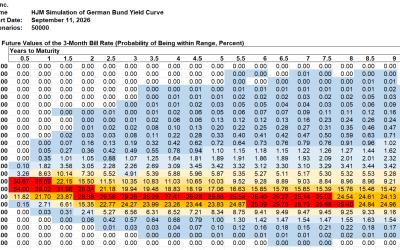
HJM++© Correlated Government Yield and Foreign Exchange Rate Simulations for Asia-Pacific, Europe and North America, September 11, 2026
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
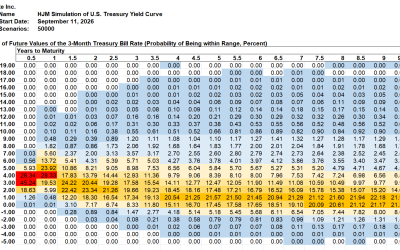
SAS Weekly Treasury Simulation, September 11 2026: Probability of 3-Month Bill Yield Over 4% in One Year Up 8% to 74%
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is up 7% to 35% today. The probability...
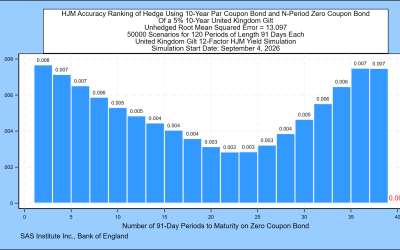
Interest Rate Hedging when Using a Multi-Factor Heath, Jarrow, and Morton Model: United Kingdom, September 4, 2026
Interest Rate Hedging when Using a Multi-Factor Heath, Jarrow, and Morton Model: United Kingdom, September 4, 2026 Donald R. van...
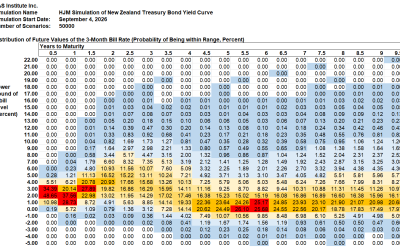
HJM++© Correlated Government Yield and Foreign Exchange Rate Simulations for Asia-Pacific, Europe and North America, September 4, 2026
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
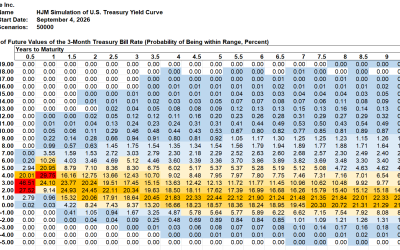
SAS Weekly Treasury Simulation, September 4, 2026: Probability of 3-Month Bill Yield Over 4% in One Year Up 22% to 66%
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is 28% today. The probability that the...
The Growing Divide in High Yield
The quality of the public high yield market has improved over the past several years, at least by conventional ratings measures....
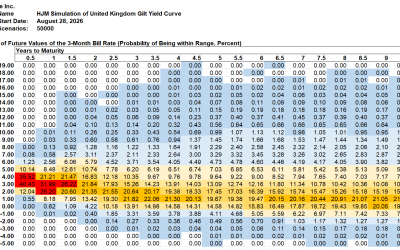
HJM++© Correlated Government Yield and Foreign Exchange Rate Simulations for Asia-Pacific, Europe and North America, August 28, 2026
The Heath, Jarrow and Morton [1992] framework for simulation and valuation using risk-free interest rates has been called “the...
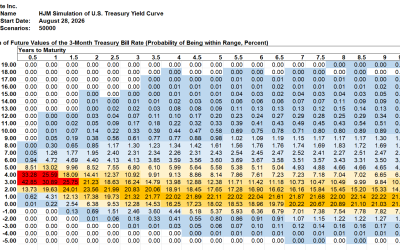
SAS Weekly Treasury Simulation, August 28, 2026: Probability of 3-Month Bill Yield Over 4% in One Year Up 6% to 44%
Summary The probability that the yield on 10-year U.S. Treasuries is over 5% in one year is 28% today. The most likely range for...